- Cabinet Decision No. 173 of 2026 officially replaces and repeals the earlier penalty structure under Cabinet Decision No. 106 of 2025.
- The new penalty structure introduces structured, proportionate tiers distinguishing minor procedural delays from deliberate non-issuance of structured XML invoices.
- Failing to appoint an Accredited Service Provider (ASP) by the mandated milestone carries an administrative penalty per violation.
- Phase 1 taxable persons (revenue ≥AED 50M) must be fully operational on 1 January 2027; Phase 2 entities (<AED 50M) must contract an ASP by 31 March 2027 ahead of 1 July 2027 go-live.
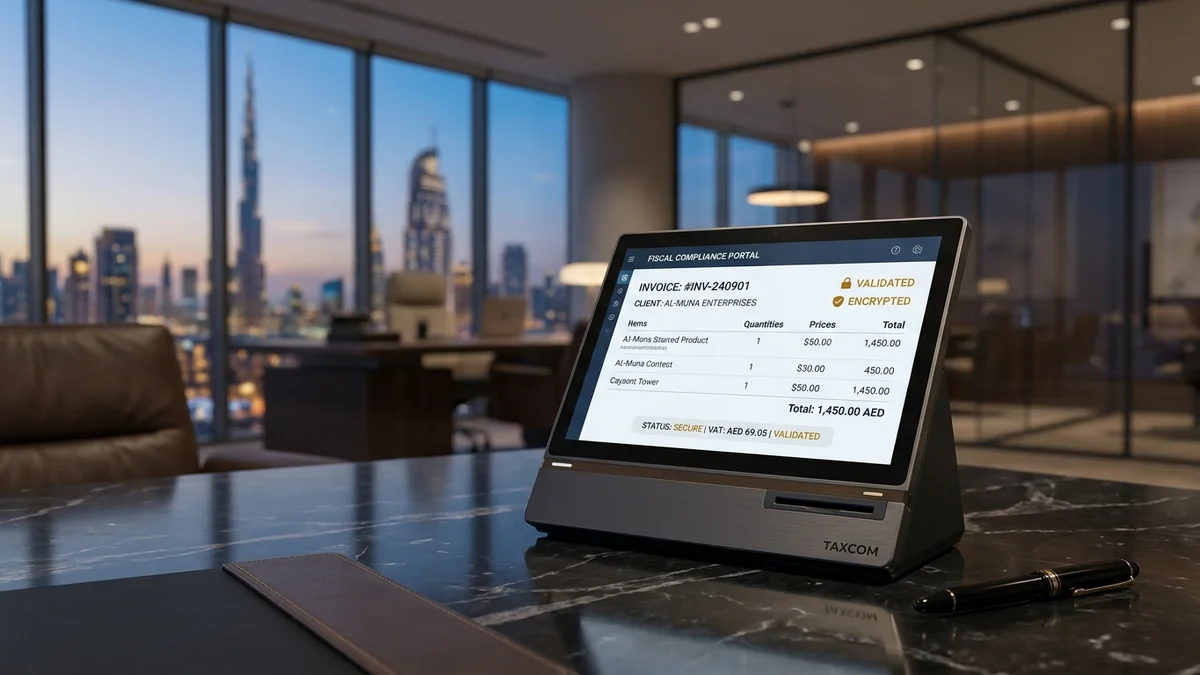
- Issuing paper invoices, standard PDFs, or unscanned digital images in place of statutory 5-corner Peppol PINT XML files once a cohort is live triggers non-compliance fines.
Table of Contents (4 Sections)
The Policy Shift: Why Cabinet Decision 106 of 2025 Was Replaced
The UAE Ministry of Finance formally released Cabinet Decision No. 173 of 2026, enacting a revised table of administrative penalties for violations of the nationwide Electronic Invoicing System and explicitly repealing Cabinet Decision No. 106 of 2025.
The regulatory overhaul followed extensive industry consultation between the MoF, the Federal Tax Authority, and major commercial chambers. The earlier 2025 framework was criticized for applying uniform, severe penalties without distinguishing between technical integration teething issues and intentional evasion.
Decision 173 of 2026 establishes a graduated, proportionate compliance framework designed to give businesses a fair runway while upholding statutory enforcement as mandatory cohorts go live.
Summary of Key Violation Categories and Penalty Tiers
Under Decision 173 of 2026, administrative penalties are segmented across three primary operational categories:
1. Failure to Contract an ASP by Mandated Milestone: Taxable persons who fail to execute an agreement with a Ministry-accredited Access Point provider by their designated cohort deadline face initial administrative warnings followed by monetary fines per month of uncontracted operation.
2. Failure to Issue Structured E-Invoices: Once a taxpayer's cohort goes live, issuing traditional paper invoices or unstructured PDFs for domestic B2B and B2G supplies is legally prohibited. Fines are assessed per non-compliant invoice, capped at statutory aggregate ceilings per tax period.
3. Transmission and Clearance Tampering: Attempting to bypass the central tax clearance platform, altering cryptographic hashes, or submitting corrupted UBL data payloads attracts elevated administrative sanctions and referral to the FTA Enforcement Directorate.
Actionable Timelines for Phase 1 and Phase 2 Cohorts
Finance leadership must align their ERP roadmaps with the updated statutory enforcement schedule:
Phase 1 Cohort (Annual Revenue ≥ AED 50,000,000): Following the ASP appointment milestone of 30 October 2026, large enterprises are undergoing ERP testing and must be fully operational on 1 January 2027.
Phase 2 Cohort (Annual Revenue < AED 50,000,000): Small and medium commercial enterprises must execute a contract with an accredited ASP no later than 31 March 2027, with mandatory live transaction clearance commencing 1 July 2027.
Integrity Chartered Auditors advises all corporate groups to conduct an immediate ERP data dictionary gap audit to ensure tax codes, TRNs, and Peppol PINT UAE schema fields conform to FTA specifications.
Practical Questions Regarding This Mandate
Does Cabinet Decision 173 of 2026 apply to retail B2C transactions?
No. Under the current mandate, real-time 5-corner electronic invoicing applies exclusively to domestic B2B and B2G supplies. Retail consumer transactions (B2C) remain excluded from real-time transmission in Phase 1 and are not subject to these penalties.
Can our company act as its own ASP without third-party accreditation?
Only if your organization undergoes the formal Ministry of Finance accreditation process under Ministerial Decision No. 244 of 2025, meets rigorous ISO security benchmarks, and connects directly to the UAE Peppol Authority. Most commercial entities contract a certified commercial ASP.
What is the consequence if our ERP system encounters a temporary network outage?
Decision 173 of 2026 provides contingency procedures: if a technical outage occurs at the ASP or ERP level, invoices must be queued and transmitted immediately upon restoration of connectivity, within statutory contingency reporting windows.
Related Advisory & Assurance Services
Majid Khalifa Almuhairi
Managing Partner · Integrity Chartered Auditors and Accountants, UAE