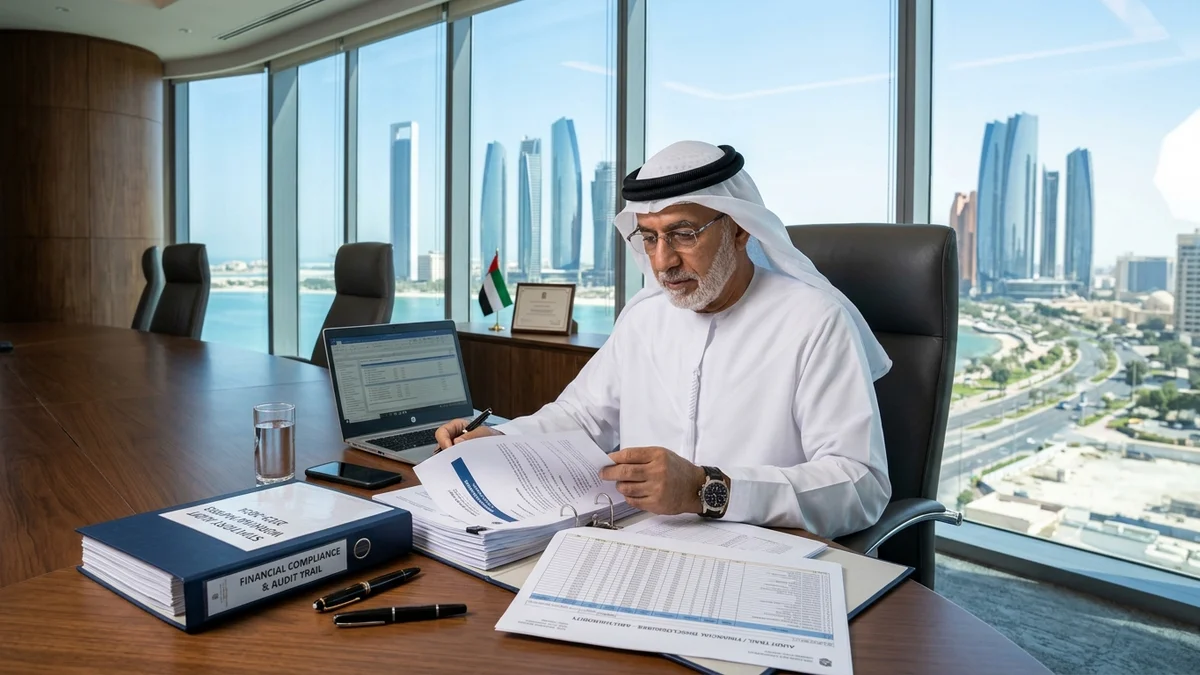
- Statutory external audits are legally mandated for all mainland LLCs and corporations registered across major UAE Free Zones.
- Early audit planning and preliminary interim testing significantly reduce year-end bottlenecks and audit fee overruns.
- Bank confirmations, physical inventory attendance, and fixed asset reconciliations represent mandatory third-party verification procedures.
- Audited financial statements are essential prerequisites for UAE Corporate Tax return submissions, bank facilities, and Free Zone trade license renewals.
Table of Contents (4 Sections)
The Statutory Mandate for External Financial Assurance
Under Articles 27 and 102 of the UAE Commercial Companies Law (Federal Decree-Law No. 32 of 2021), mainland commercial companies—including Limited Liability Companies (LLCs) within the law's scope—must appoint a licensed independent auditor registered with the UAE Ministry of Economy to conduct an annual examination of their financial statements, without an AED 50M revenue threshold.
Separately, under UAE Corporate Tax law (Article 54(2) of Federal Decree-Law No. 47 of 2022 and Ministerial Decision No. 84 of 2025, which supersedes Ministerial Decision No. 82 of 2023 for tax periods starting on or after 1 January 2025), taxable persons deriving revenue exceeding AED 50,000,000 in a relevant tax period, all Corporate Tax Groups, and all Qualifying Free Zone Persons (QFZPs) seeking the 0% Corporate Tax rate regardless of revenue, are statutorily mandated to prepare and maintain audited financial statements.
Furthermore, Free Zone authorities including ADGM, DIFC, DMCC, JAFZA, and DDA mandate annual submission of audited accounts as a strict condition for commercial license renewal and corporate good standing.
The Year-End Audit Readiness Checklist
Finance teams can streamline audit fieldwork by preparing key schedules prior to partner review:
1. Bank Confirmations & Reconciliations: Initiating direct bank balance and facility certificates with all banking institutions.
2. Revenue Cut-Off Testing: Documenting shipping terms, service completion certificates, and contract milestones surrounding year-end.
3. Related Party Disclosures: Documenting intercompany loan agreements, director remunerations, and arm’s length justification.
4. Accruals & Provisions: Calculating employee end-of-service gratuity liabilities under UAE Labour Law and expected credit loss (ECL) provisions under IFRS 9.
Integrity Chartered Auditors Delivery Assurance
Our partner-led external audit team delivers rigorous, independent statutory audits compliant with International Standards on Auditing, providing boards and financial institutions with unquestioned assurance.
Practical Questions Regarding This Mandate
Which entities in the UAE are legally required to undergo an annual external audit?
Under Federal Decree-Law No. 32 of 2021 on Commercial Companies, all mainland LLCs, Public and Private Joint Stock Companies, foreign branches, and entities licensed in most UAE Free Zones (including DMCC, JAFZA, DAFZA, DIFC, and ADGM) must be audited annually by a licensed auditor registered with the Ministry of Economy.
What is the statutory deadline for completing the annual audit?
Under the Commercial Companies Law, audited financial statements must generally be presented to the annual general assembly within 4 months of the financial year-end. For Corporate Tax purposes, audited accounts must support the tax return filed within 9 months.
How are employee end-of-service benefits audited under UAE Labour Law?
Auditors verify end-of-service gratuity (EOSG) calculations against individual employee contract commencement dates, basic salaries, UAE Labour Law formulas (Federal Decree-Law No. 33 of 2021), or actuarial assessments where defined benefit valuation is required under IAS 19.
Related Advisory & Assurance Services
Statutory & External Audit
Independent statutory financial statement audits in compliance with ISA and IFRS for mainland and free zones.
Internal Audit & Risk Advisory
Risk governance evaluations, internal control gap assessments, and board audit committee reporting.
Raza Ali (ACCA)
Audit Supervisor · Integrity Chartered Auditors and Accountants, UAE